A credit report is easier to understand when you treat it as a record to verify, not a verdict on your finances. The layout differs among bureaus, but the questions are consistent: Does this information belong to you? Is each account’s balance, status and payment history accurate? Is there anything you do not recognize?
You can request your reports from all three nationwide bureaus for free each week through AnnualCreditReport.com. Save each one with its bureau name and date. You will then have a record to compare with statements and future reports, even if you do not review every bureau in one sitting.
Key Takeaways
- Start with the identity and account sections. Verify names, addresses, lenders, balances, limits, status and payment history.
- Check all three bureaus. A lender may not report the same information to Equifax, Experian and TransUnion.
- Read codes in context. A “30” in a payment grid commonly means 30 days past due, but use the legend on that bureau’s report.
- Investigate, then dispute. An unfamiliar item deserves checking; an outdated balance alone may reflect a reporting delay.
- Protect yourself if you suspect fraud. Fraud alerts, credit freezes and the identity-theft blocking process serve different purposes.
Get Your Reports Before You Start
Use the federally authorized AnnualCreditReport.com portal to obtain free credit reports from Equifax, Experian and TransUnion. The three bureaus offer free online reports weekly. You can request them together or space them out. If online identity verification fails, the official phone or mail request process is another option.
Keep copies in a secure place and record the date each report was generated. A credit report does not necessarily include a credit score: FICO and VantageScore are scoring products calculated from reported information. If you compare scores from different services, note both the scoring model and the date.
Read Each Section in Order
The illustration below uses entirely fictional information. It shows where to look, not the exact layout of an Equifax, Experian or TransUnion report.
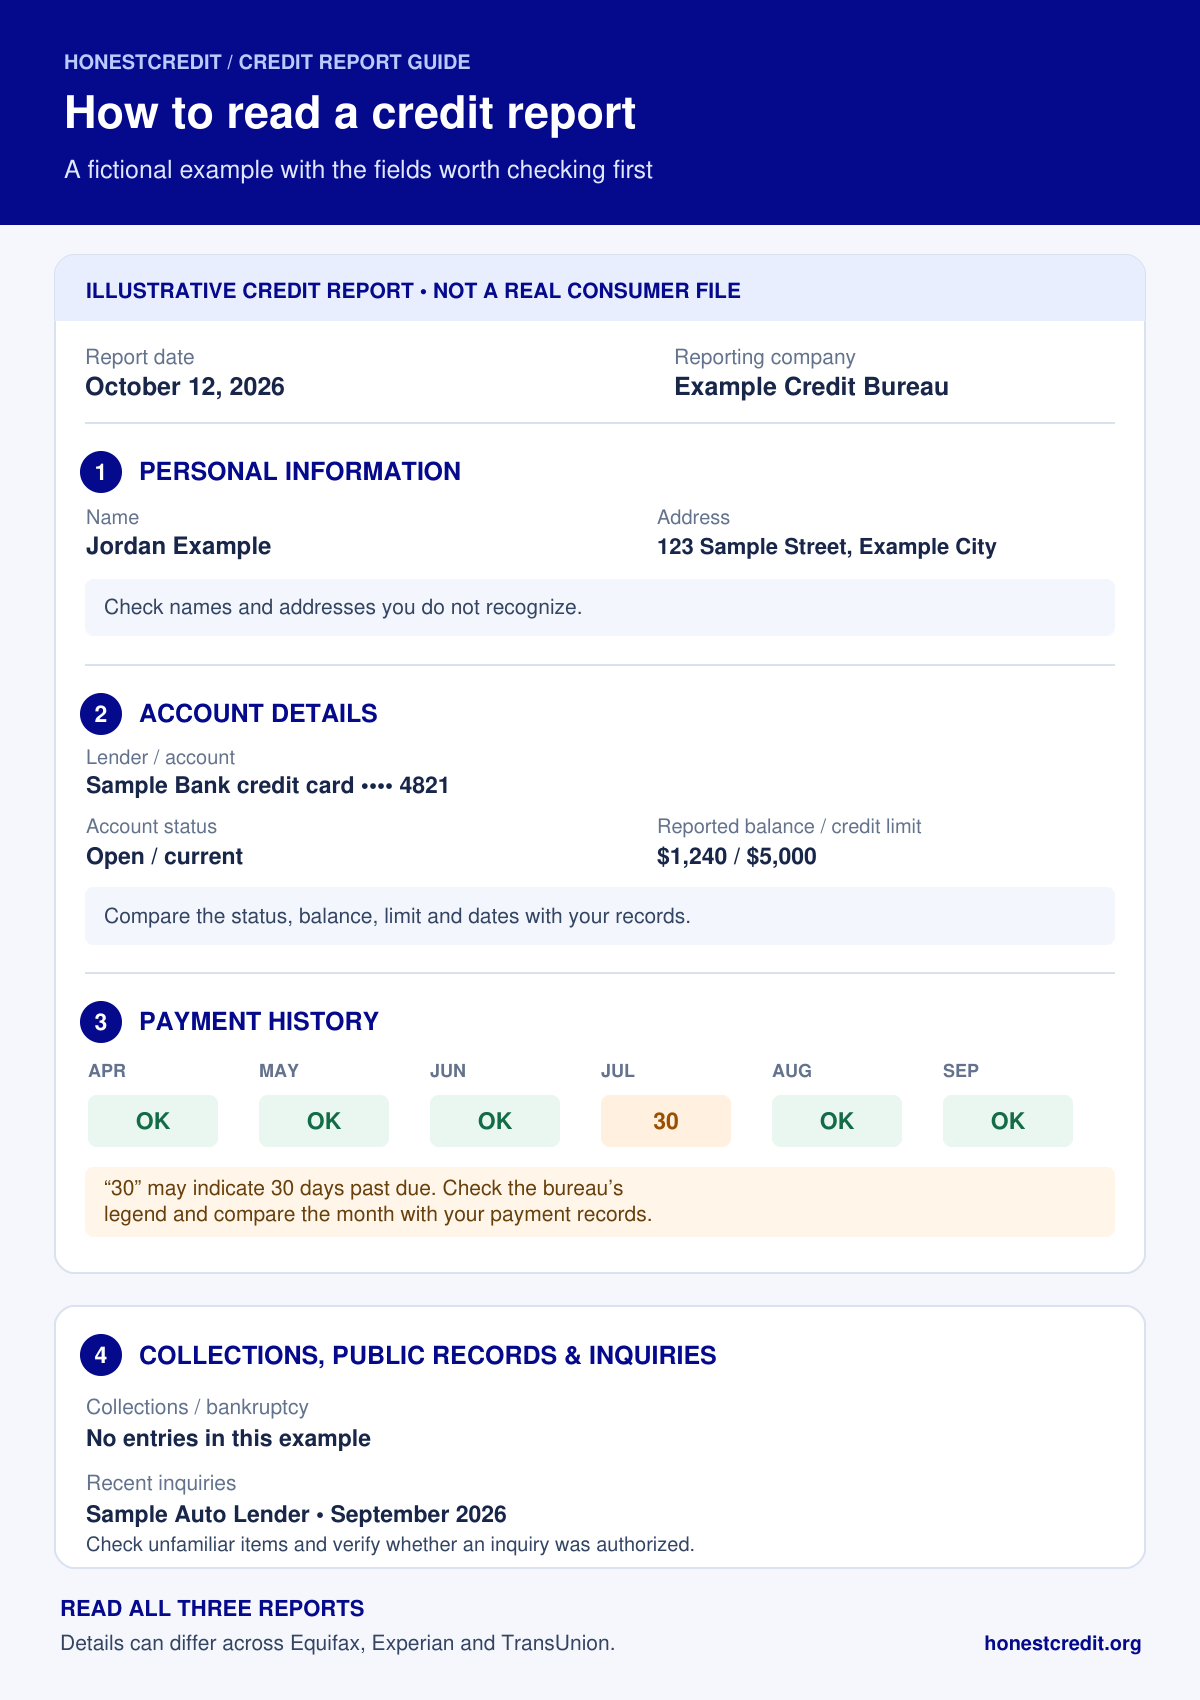
1. Personal information. Check your name, former names, address history, birth date and other identifying details shown. An old address or minor typo is not automatically evidence of fraud. A name or address belonging to someone else, especially alongside an unfamiliar account, may point to a mixed credit file or identity theft.
2. Accounts. For each credit card or loan, compare the lender, masked account number, account type, date opened, balance, credit limit or original loan amount, and whether the account is open, closed or past due. Check your own statements against the month and balance the lender last reported. A payment made yesterday may not yet appear on a report updated during a prior reporting cycle.
3. Payment history. Look at the month-by-month grid and any key printed on the report. A recent “current” status does not erase a previously reported late month. Conversely, a late-payment mark for a month in which you paid on time deserves a closer look. The example illustration shows “30” in July as a fictional late-payment entry, followed by current months.
4. Collections and public records. Compare any collection with the underlying creditor, amount, dates and your records. An original creditor account and a separate collection entry can both appear in connection with the same debt; their presence alone does not establish an error. Bankruptcy information may appear in the public-record portion of a report. Verify its chapter, filing date and status against the case record.
5. Inquiries. Look for credit applications you recognize. Checking your own report is a soft inquiry and does not hurt your score; an application-related hard inquiry can affect some scores. An unfamiliar hard inquiry deserves investigation, though an unfamiliar company name can sometimes be a lender’s financing partner.
Understand the Codes and Dates
Credit reports compress years of account activity into short labels. The bureau’s own legend is the first place to interpret a code. The examples below describe common payment-history labels, not a universal codebook.
| Example label | What to check |
|---|---|
| OK or current | The account was reported as current for that period. Confirm the month shown. |
| 30, 60 or 90 | Commonly indicates days past due. Compare that specific month with your payment records. |
| CO or charge-off | May identify an account the creditor wrote off as a loss. It does not necessarily mean the debt disappeared. |
| No data or blank | The bureau may have no payment information for that month. Check the report’s key before treating a blank as a missed payment. |
Also look at the dates opened, closed, last reported and, for a delinquent account, the date of first delinquency when available. Those dates answer different questions. A recently updated collection is not automatically a newly incurred debt, and a balance that has not caught up with a recent payment is not automatically an error. Compare the date on the report with your documents before filing a dispute.
Check for Errors and Fraud Signs
Work through each report with a short list of items to verify:
- Names, addresses or accounts you do not recognize.
- Balances, limits or past-due amounts that conflict with records for the reporting period.
- Payments marked late despite evidence they were made on time.
- Accounts marked open, closed, paid or charged off in a way that conflicts with the lender’s records.
- Collections with questionable amounts, ownership or delinquency dates.
- Hard inquiries you cannot connect to an application.
- Bankruptcy information with an incorrect chapter, filing date or status.
Write down the bureau, account name, disputed field, reason and documents supporting each concern. Avoid a broad claim such as “everything on this account is wrong” when the issue is one particular balance or month. An unfamiliar account or address may warrant identity-theft steps immediately; an older balance may simply need you to check the lender’s reporting date first.
Dispute Information That Is Wrong
If the information is inaccurate or incomplete, dispute the specific error with each bureau displaying it. You can also dispute with the furnisher, such as the lender or collector that supplied the data. Include identifying information, the account and field at issue, a clear explanation and copies of supporting records. Keep copies of what you submit and any confirmation or mailing proof.
A bureau generally has 30 days to investigate a dispute, though some circumstances allow up to 45 days. It must pass relevant dispute information to the furnisher. Review the investigation result and your updated report rather than assuming the item was corrected everywhere. If another bureau shows the same error, check that report separately.
For a CFPB complaint about inaccurate or incomplete information in a consumer report, current complaint instructions generally require you to dispute with the reporting company first and wait until the dispute is no longer pending or more than 45 days have passed. This complaint process is distinct from your right to dispute with the bureau.
Take Extra Steps for Identity Theft
If an account is not yours, a normal accuracy dispute may not be the only path. Create an identity-theft recovery plan at IdentityTheft.gov and consider the Fair Credit Reporting Act’s blocking procedure. When a credit reporting company receives the required Identity Theft Report, proof of identity and identification of fraudulent items, the law generally requires it to block qualifying information within four business days. The required submission matters; merely calling an item fraudulent does not start that deadline.
A fraud alert tells lenders to take additional steps to verify your identity before opening new credit. An initial alert lasts one year, while eligible identity-theft victims can request an extended alert. A security freeze restricts access for many new-credit decisions until you lift it. Freezes are free, must be placed separately with each bureau and do not affect your credit score or existing accounts. Choose the protection that fits the situation; a freeze does not correct an inaccurate account already on a report.
Understand Medical Collections
Medical collections need particular care because bureau policies and federal rules are not the same thing. The three nationwide bureaus removed paid medical collections, stopped reporting medical collections with an initial reported balance under $500 and delayed reporting eligible unpaid medical collections for one year. A broader CFPB rule finalized in January 2025 was vacated by a federal court on July 11, 2025; it is not a current blanket ban on medical debt in reports.
If a medical collection appears, check its initial amount, payment status and reporting dates against the applicable bureau policy and your records. A larger unpaid collection may still appear. Document and dispute information that is inaccurate or inconsistent with the applicable reporting policy rather than assuming every medical bill must be absent.
Keep a Repeatable Review Routine
After the first review, keep a private list of the accounts and fields you checked. Compare a later report against that list if you are monitoring a dispute, preparing to apply for credit or watching for identity theft. Recheck all three bureaus when the distinction matters: an item can appear on one report and be absent from the others.
The aim is to recognize what belongs on your file and act on what does not. You do not need to memorize every code or dispute every unfamiliar abbreviation. Use the bureau’s legend, the account’s reporting date and your own records to decide what needs attention.
Frequently Asked Questions
Where can I get my reports for free?
AnnualCreditReport.com is the federally authorized portal for reports from Equifax, Experian and TransUnion. The bureaus offer free online reports each week.
Does checking my own report hurt my credit score?
No. Requesting or reviewing your own report is a soft inquiry and does not affect your score.
What does “30” mean in payment history?
It commonly indicates an account reported 30 days past due for the month shown. Check that bureau’s legend and your payment records before concluding the entry is wrong.
What if an address on my report is unfamiliar?
Check whether it is an old address or a reporting mistake. If it belongs to someone else, review the rest of the file for unfamiliar accounts or inquiries and contact the affected bureau. A pattern of information that is not yours may suggest a mixed file or identity theft.
How long does a credit report dispute take?
A bureau generally has 30 days to investigate, with up to 45 days in some circumstances. Keep the confirmation and review the result and updated report.
Does a free credit report include my score?
Not necessarily. A report lists credit-history information, while a credit score is calculated separately under a particular scoring model.
Sources
- AnnualCreditReport.com: official free reports portal
- FTC: Understanding Your Credit
- TransUnion: How to Read Your Credit Report
- TransUnion: payment-history codes and report key
- Experian: Charge-Off Status and Debt
- CFPB: How to Dispute an Error on Your Credit Report
- CFPB: Dispute Investigation Timelines
- CFPB: Credit Reporting Complaint Notice
- CFPB: Identity-Theft Blocking Process
- FTC: Credit Freezes and Fraud Alerts
- TransUnion: Nationwide Bureau Medical-Collection Policies
- CFPB: Medical-Debt Rule Vacatur