Hard vs. Soft Inquiries

Hard vs. Soft Inquiries: What They Do to Your Score

Hard inquiries usually appear when you apply for new credit and a lender checks your credit file for that application; they can modestly affect a score for a limited period. Soft inquiries—including checking your own credit and many prescreening or […]
Credit Utilization

Credit Utilization: What It Is and How to Cut It

Credit utilization is the percentage of available revolving credit that your credit reports show you are using. Scoring models can evaluate utilization across all revolving accounts and on individual cards, but there is no universal 30% cutoff where a score

Couple reviewing bills and payment records on a laptop

Payment History: The #1 Credit Score Factor

Payment history is the largest of FICO’s five general score-factor categories, at about 35% for the typical population. A payment can be late to the creditor before it becomes a 30-day delinquency on a credit report, so fix a missed

FICO vs. VantageScore: What’s Different and What Matters

FICO and VantageScore are competing families of credit scores built from credit-report data. Most base consumer versions use a 300–850 range, but the same person can receive different numbers because the model family, model version, credit bureau, and date of

Credit Basics for Beginners

Credit Basics for Beginners: How Credit Works

Credit reports are the records of your borrowing and repayment history; credit scores are risk estimates calculated from those reports. For most consumers, the strongest credit habits are simple: pay every account on time, keep revolving-card balances modest relative to

How to Raise Your Credit Score Fast

How to Raise Your Credit Score Fast

The fastest legitimate credit-score improvements usually come from correcting inaccurate report data and reducing high revolving balances before the next bureau update. Preventing a new late payment is even more important. There is no guaranteed number of points or universal

What Is a Good Credit Score and Why It Matters

What Is a Good Credit Score and Why It Matters

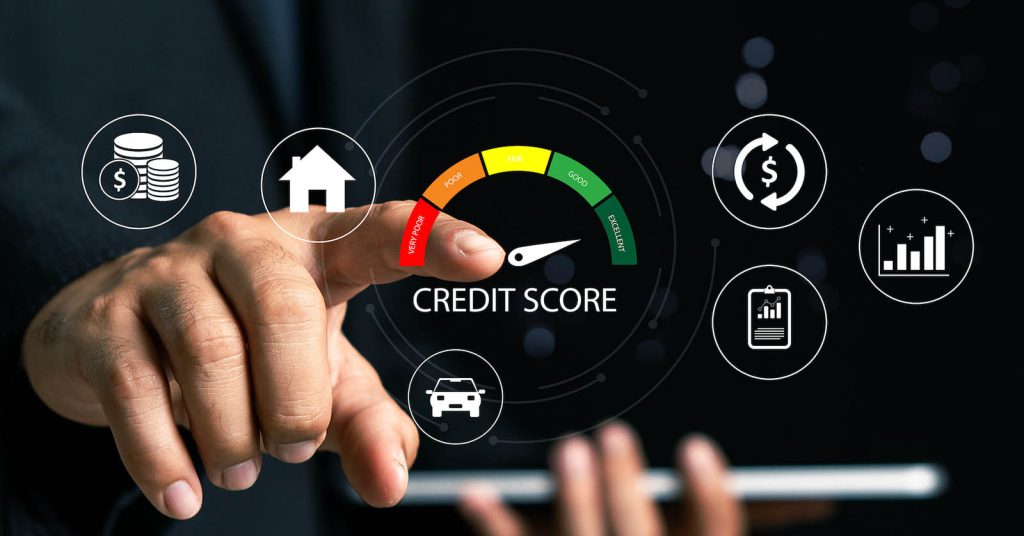
On FICO’s 300–850 base-score scale, 670–739 is labeled Good, 740–799 Very Good, and 800–850 Exceptional. Those labels are useful reference points, not lender approval rules: lenders choose their own score model, version, cutoffs, and other underwriting criteria. Experian’s 2025 Consumer