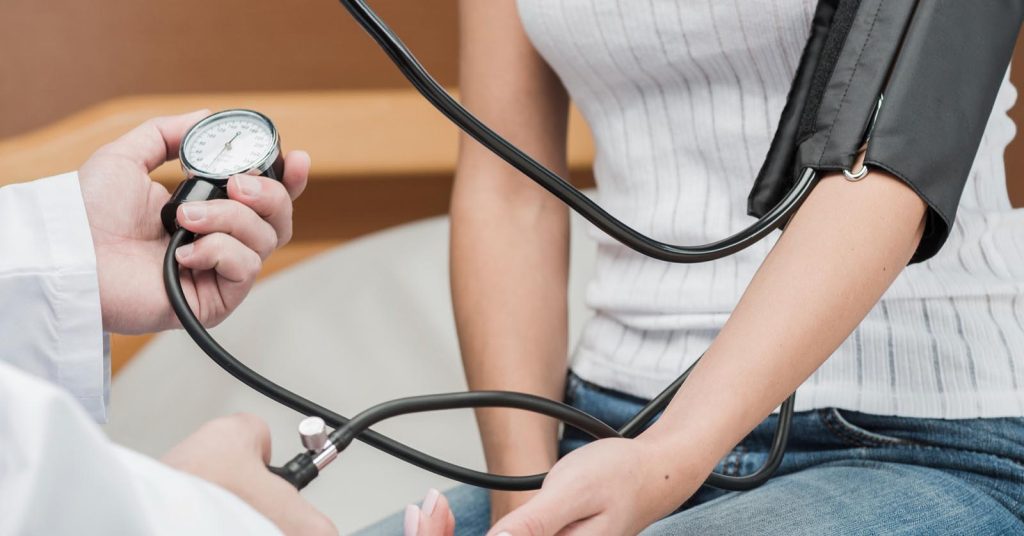
The appointment is usually brief, but its results can influence years of premiums. Treat it as a collection of current underwriting evidence rather than a pass-or-fail physical. The insurer combines the exam with the application and other permitted records before deciding what offer, if any, it can make.
Before Scheduling: Confirm What the Insurer Requires
Not every application follows the same path. An insurer may waive the exam, order a paramedical appointment, request records from treating physicians, or require additional testing. Age, benefit amount, policy type, disclosed history, and the insurer’s underwriting rules can affect the request.
Ask who will contact you, where the exam can occur, whether fasting is required, and what identification or records to bring. Verify that the examiner is working for the insurer or its authorized vendor before sharing health information.
The insurer generally pays for an exam it requires for the application. Be cautious if an unexpected caller asks for payment or financial credentials without a confirmed connection to the insurer.
Prepare Information, Not a Temporary Health Performance
Collect information that helps the examiner record an accurate history:
- Government-issued identification
- Names, dosages, and purposes of medications and supplements
- Doctors’ and clinics’ names, addresses, and phone numbers
- Dates and outcomes of major diagnoses, tests, surgeries, and hospital stays
- Family medical history requested on the application
- Details of tobacco, nicotine, alcohol, or other substance use when asked
Follow the scheduling company’s instructions about food, water, exercise, caffeine, alcohol, and medications. Do not fast unless instructed, and do not stop or change prescribed treatment for an insurance exam. A temporary change can be unsafe and does not replace accurate disclosure.
During the Appointment: Expect Questions and Measurements
A paramedical professional may review the health questions already asked on the application. Repetition helps the insurer confirm dates, treatments, and current status; it is not a reason to give a shorter or different answer.
The physical portion often includes height, weight, pulse, and blood pressure. Blood and urine samples are common. Some insurers may request saliva, an electrocardiogram, cognitive or mobility screening, or other tests based on age, health history, and the amount applied for.
The appointment is not a substitute for medical care. The examiner collects information under the insurer’s protocol and normally does not diagnose conditions or recommend treatment.
Blood and Urine Results Support Risk Classification
Laboratory testing can provide information related to blood sugar, cholesterol, liver and kidney function, nicotine exposure, certain medications, and other health or substance-use indicators. The panel is not identical for every application.
A single value does not necessarily determine the decision. Underwriters can consider patterns, treatment, control of a condition, physician records, age, and other evidence. Insurers also use different guidelines, so the same medical history can produce different results.
Be precise about nicotine products, including cigarettes, cigars, vaping products, chewing tobacco, and nicotine replacement when asked. Each insurer defines its tobacco or nicotine classes under its own rules; guessing can create a mismatch with laboratory results.
After the Exam: The Underwriter May Need More Evidence
The exam company sends the required information to the insurer. The underwriter may then request an attending physician statement, additional records, clarification, or another test. A follow-up request is not automatically a negative decision.
Processing time depends on how quickly records arrive, whether information conflicts, and the complexity of the case. Respond to documented requests and confirm that medical providers have the correct authorization. Repeatedly submitting new applications during a delay can create more records without solving the original question.
You may be able to obtain laboratory results or other exam information through the insurer or exam vendor. Procedures vary. Share unexpected results with your health care professional rather than interpreting an insurance panel on your own.
The Exam Influences the Offer, Not Just Approval
Underwriting can result in the requested offer, a different rate class, an extra premium, a lower available amount, a postponement, or a decline. The final decision also reflects nonmedical factors such as occupation, hazardous activities, driving history, travel, and the policy requested.
Compare the issued offer with the original request. A preliminary quote can assume a favorable class that the completed underwriting does not support. Keep policy terms consistent when comparing life insurance quotes after final offers arrive.
If an insurer takes an adverse action using a consumer report or another covered source, the notice should explain applicable consumer rights and how to contact the reporting company. Request and dispute inaccurate information through the process identified in the notice.
Do Not Try to Game the Measurements
Normal preparation can reduce avoidable noise: follow fasting instructions, avoid an unusually strenuous workout immediately before the appointment, arrive hydrated when permitted, and allow time to sit calmly before a blood-pressure reading.
Short-term tactics cannot erase a documented medical history and may create inconsistent results. More importantly, hiding a diagnosis, medication, nicotine use, or recent treatment can affect underwriting and a later claim. Accurate context is more valuable than an artificially favorable reading.
If an acute illness or unusual event could distort the exam, tell the scheduling company before the appointment. The insurer can decide whether rescheduling or adding context is appropriate.
Consider No-Exam Coverage as a Separate Tradeoff
An applicant who cannot schedule an exam or strongly prefers to avoid one can compare no-exam life insurance. Accelerated underwriting, simplified issue, guaranteed issue, and group coverage do not offer the same acceptance rules or contract value.
Skipping the appointment does not necessarily remove health review. External data and health questions can replace the physical exam, and the insurer may refer an accelerated application to traditional underwriting.
Compare death benefit, premium, duration, guarantees, graded-benefit provisions, and the effective date. Convenience is useful only if the resulting policy meets the actual protection need.
Review the Final Policy Before Accepting It
Read the premium, underwriting class, benefit amount, duration, riders, exclusions, and application attached to the policy. Correct any error through the insurer’s formal process. Do not write changes on the contract and assume they are accepted.
A better-than-expected offer is welcome, but affordability still matters. A less favorable offer may justify comparison with another insurer, a different amount, or a different policy design. Never cancel existing coverage while a new application is pending.
Use the policy’s applicable review period to confirm that the issued contract matches the decision. Coverage becomes dependable through accurate underwriting, accepted terms, required payment, and continued maintenance, not merely by completing the exam.
Frequently Asked Questions (FAQs)
How long does a life insurance medical exam take?
Many paramedical appointments are relatively brief, but the required procedures vary. Ask the exam provider for the expected duration and whether additional testing is scheduled.
Do I have to fast before a life insurance blood test?
Only if the insurer or exam provider instructs you to fast. Follow the stated time window and ask whether water and medications are permitted. Do not improvise a fasting plan.
Can I use my own doctor for the exam?
Usually not for the scheduled insurance exam. The insurer typically arranges its own examiner or approved facility and may separately request records from your doctor. Confirm the procedure before scheduling anything independently.
Can I be denied because of one abnormal result?
It is possible for a result to affect the decision, but insurers generally evaluate the full application and their own underwriting guidelines. They may request clarification, more records, or repeat testing before deciding.
Will taking an exam guarantee a lower premium?
No. An exam can provide evidence that supports a favorable class, but it can also confirm risks that raise the price or affect eligibility. Compare the final offer with suitable no-exam and traditionally underwritten alternatives.