Handing someone your keys feels simple. The insurance question is not.
The most important distinction is between an occasional borrower and someone who is effectively another regular driver of the vehicle. Policies are often written to tolerate occasional permissive use, but insurers also expect to know about people who live in the household or routinely have access to the car.
Permission Is the First Coverage Question
When a friend or relative borrows your car with your permission, your auto policy may extend liability and other applicable coverage to that driver. Texas personal-auto filing requirements, for example, require policy language to provide coverage for people outside the household who use a covered automobile with permission.
That does not create one nationwide rule for every policy. The driver still has to fall within the policy’s definition of an insured or permissive user, and the use has to stay within whatever limits the contract places on permission, vehicle use, territory, and excluded activities.
An Occasional Borrower Is Different From a Regular Driver
Insurers price a policy partly around who is expected to drive the car. A driver who uses the vehicle once for an errand presents a different exposure from a spouse, roommate, adult child, caregiver, or partner who drives it every week.
New York’s Department of Financial Services notes that insurers may consider resident operators when rating a policy because household members can create an ongoing exposure. Other states and insurers use their own rules for when a household or regular driver must be disclosed or listed.
Do not rely on the word “occasional” without checking the actual policy. If another person drives the car repeatedly, keeps a key, commutes in it, uses it whenever another vehicle is unavailable, or effectively treats it as a shared vehicle, tell the insurer and ask whether that driver needs to be added.
Household Members Deserve Extra Attention
A household member can be treated differently from a visiting friend. Applications commonly ask about licensed residents and regular operators because their access to the vehicle can affect underwriting and price.
Leaving a regular household driver off the policy is not the same thing as having a harmless occasional guest. If the insurer expected that driver to be disclosed, a claim can become more complicated and the policy can face underwriting consequences.
What Happens If the Borrower Causes a Crash?
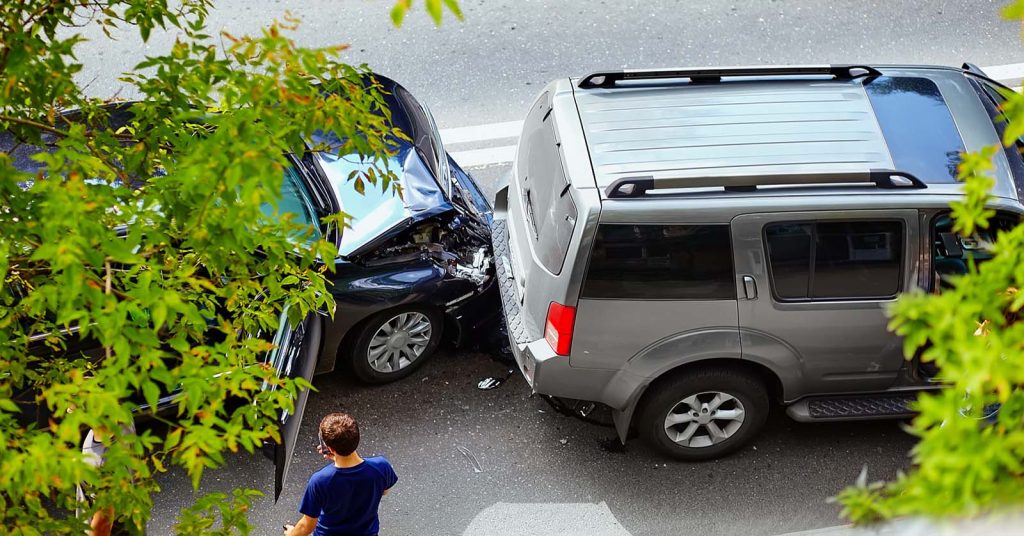
If the driver qualifies for coverage under your policy, the coverages attached to your car generally determine what protection is available. Liability can respond to injuries or property damage the borrower causes to others, subject to the policy limits and terms. Collision may address damage to your own car if you carry it and the loss qualifies, usually subject to the deductible.
| Loss after a covered borrower crashes your car | Coverage that may respond |
|---|---|
| Injuries the borrower causes to another person | Your bodily injury liability coverage, subject to who qualifies as an insured and the policy limits |
| Damage the borrower causes to another vehicle or property | Your property damage liability coverage, subject to policy terms and limits |
| Damage to your own car from the collision | Your collision coverage if you carry it and the loss is covered, minus the applicable deductible |
| Injuries to people in your car | PIP, MedPay, liability, health insurance, or another source may apply depending on fault, state law, and the policy |
A claim under your policy can still affect your insurance record or future pricing where state law and insurer rules allow. Lending the car therefore transfers more than the steering wheel; it can expose your own policy limits, deductible, and claim history.
The Borrower’s Insurance May Be Relevant, but Do Not Assume the Order
A borrower who has their own auto policy may have coverage that applies after or alongside the vehicle owner’s policy. Which policy is primary, excess, or unavailable depends on the contracts and state law.
The familiar phrase “insurance follows the car” is a useful starting point, not a complete coverage analysis. A driver’s own liability policy may matter when the owner’s limits are exhausted or when the owner’s policy does not cover a particular situation. A non-owner policy can also provide liability-focused protection for someone who does not own a car but regularly drives vehicles they do not own.
After a serious crash, report the loss promptly and let the insurers determine how their policies coordinate rather than promising each other in advance that one company “will definitely pay second.”
Situations Where Lending the Car Can Create a Coverage Problem
Permission alone does not cure every policy problem. Pay particular attention when:
- The driver is specifically excluded. An excluded-driver endorsement can remove coverage when that named person drives the vehicle.
- The driver lives with you but is not disclosed. Household-driver rules vary, but regular resident operators are a common underwriting concern.
- The person uses the car regularly. Repeated use can fall outside the idea of an occasional permissive borrower.
- The use is commercial or app-based. Delivery, rideshare, or other business activity can trigger exclusions or require different coverage. Rideshare insurance addresses a different use than lending a car to a friend for a personal errand.
- The driver does not have a valid license. Knowingly allowing an unlicensed or suspended driver to use the vehicle can create serious legal and insurance problems.
- The driver takes the car without permission. Non-permissive use raises a different coverage question from an ordinary loan of the vehicle.
Policy language matters most in these edge cases. Read the definitions and exclusions rather than relying on a general statement that “anyone I let drive is covered.”
Before You Lend Someone Your Car
You do not need an insurance investigation every time a trusted friend moves your car out of a driveway. But a few checks are worth making before a longer loan or recurring arrangement.
- Confirm that the driver is licensed.
- Know whether the person lives with you or uses the car regularly. If so, ask the insurer whether they must be listed.
- Check for any named-driver exclusion.
- Review your liability limits. A borrower can create a claim against the same limits that protect you.
- Know whether you carry collision. Liability alone does not pay to repair your own car after an at-fault collision.
- Ask about the purpose of the trip. Personal borrowing is different from rideshare, delivery, or other commercial use.
- Set practical limits. Be clear about who may drive, how long they may keep the vehicle, and where it may be used.
If the arrangement is becoming routine, the safer insurance solution is usually to disclose the real driving pattern and let the insurer tell you how the person should be classified. Hiding a regular driver to keep the premium lower can create a much larger problem at claim time.
Frequently Asked Questions (FAQs)
Does my car insurance cover a friend who borrows my car?
It often can when the friend has your permission and is an occasional driver, but coverage depends on the policy and state rules. Confirm any permissive-use limits, exclusions, and household-driver requirements before assuming the answer is yes.
Do I need to add someone who only drives my car occasionally?
Not always. A true occasional borrower may be covered without being listed, while a household member or regular operator may need to be disclosed or added. Ask the insurer when the driving pattern becomes recurring.
What if someone borrowing my car has their own insurance?
Their policy may be relevant, but it does not automatically replace yours. The vehicle owner’s policy often plays an important role first, while the borrower’s insurance may provide additional or excess protection depending on the contracts and state law.
Will my collision coverage pay if my friend crashes my car?
It may if the friend qualifies as a covered driver, the crash is a covered collision loss, and you carry collision coverage on the vehicle. Your deductible and other policy terms would still apply.
Is an excluded driver covered if I give them permission?
Usually the point of a valid named-driver exclusion is to remove coverage for that person even if they have access to the vehicle. State rules differ, so read the actual endorsement and do not let an excluded driver use the car based on a general permissive-use assumption.