Expensive home-insurance surprises do not always come from dramatic exclusions. Sometimes the policy covers the event but only up to a small special limit. In other cases, the resulting damage is covered while the worn-out part that caused it is not. And sometimes a risk that is commonly insured in one state or ZIP code is carved out in another.
So the better question is not simply “Is this covered?” It is: What caused the loss, which part of the policy applies, what does the policy take back through exclusions, and is there another policy or endorsement for the gap?
| Risk or property | Standard homeowners policy | Possible way to address the gap |
|---|---|---|
| Flood from surface water, storm surge or overflowing waterway | Generally excluded | NFIP or private flood insurance |
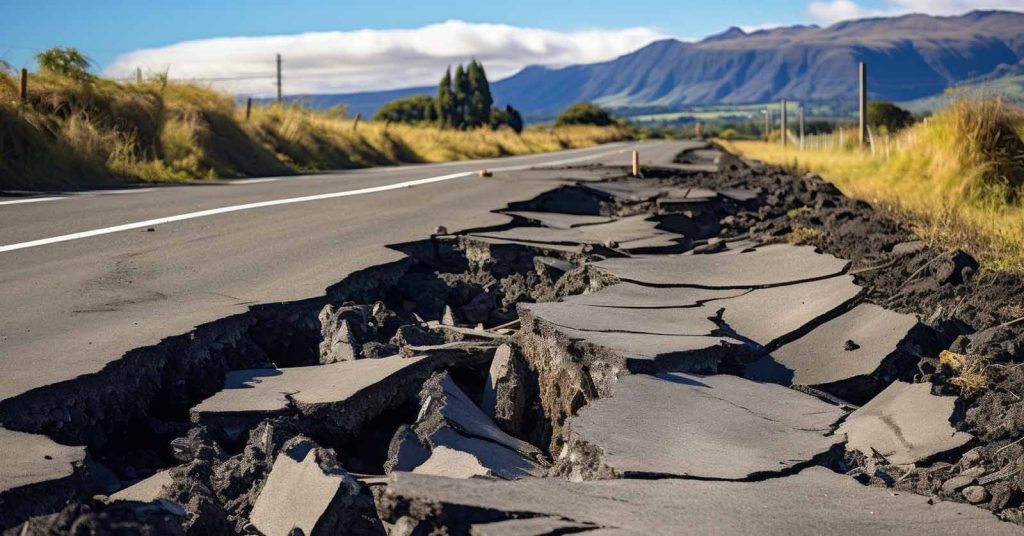
| Earthquake and earth movement | Generally excluded | Earthquake endorsement or separate policy where available |
| Wear and tear or poor maintenance | Not insurance losses | Maintenance and household savings |
| Termites, rodents and other infestations | Generally excluded | Prevention, treatment and maintenance |
| Sewer, drain or sump backup | Often excluded from the base policy | Water-backup endorsement where available |
| Expensive jewelry, art and similar valuables | May be covered only up to special limits | Scheduled personal-property coverage |
| Home-business property or liability | Can be limited or excluded | Home-business endorsement or business policy |
| Wind in certain coastal/high-risk markets | Can be excluded even though wind is commonly covered elsewhere | Separate windstorm coverage where available or required |
An Exclusion Is Different From a Limit or Deductible
Before looking at individual gaps, separate four different reasons an insurer might pay less than expected.
- Exclusion: Your policy removes coverage for a specified cause of loss, property, activity or circumstance.
- Special limit or sublimit: The loss may be covered, but only up to a lower maximum than the overall Coverage A or Coverage C limit.
- Deductible: Coverage exists, but you retain the stated first portion of the covered property loss.
- Condition: Coverage can depend on duties or circumstances described in the policy, such as protecting damaged property or complying with certain vacancy provisions.
Exclusions identify perils and losses the policy does not insure and can narrow what the insuring agreement initially appears to provide.
A $300,000 dwelling limit does not mean every type of $300,000 home loss is insured.
Flood Is One of the Biggest Homeowners Insurance Gaps
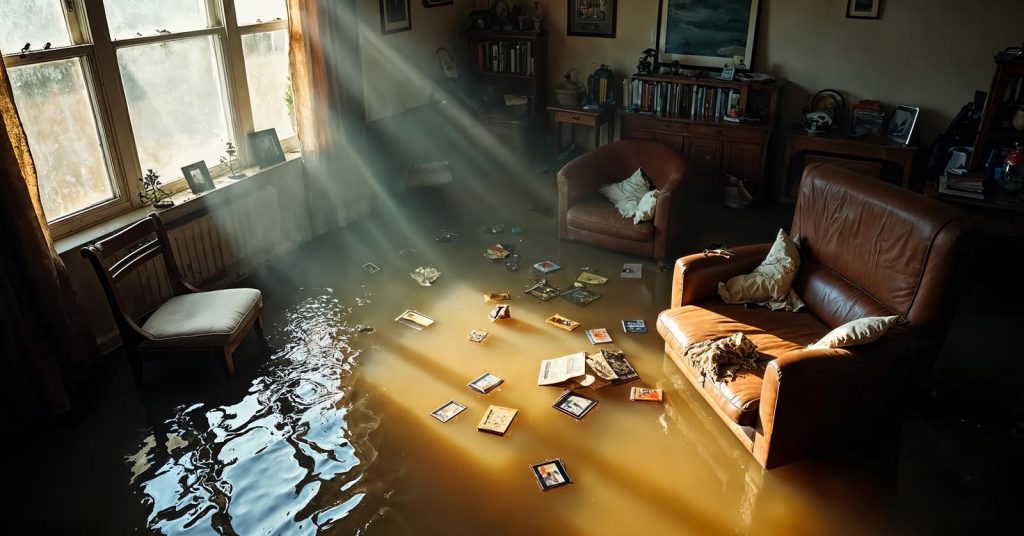
Most homeowners insurance does not cover flood damage.
Flood insurance is separate because a standard homeowners policy generally excludes flooding such as:
- Storm surge
- Overflowing rivers or streams
- Flash flooding
- Rapid accumulation or runoff of surface water
- Other qualifying external flooding
A burst pipe inside the house is a different water-loss category. Homeowners insurance often covers sudden and accidental internal water damage, subject to policy terms. Standing water on the floor does not make two losses the same insured event.
The dividing line between flood and homeowners insurance depends on the source and movement of the water, not simply on how the damage looks.
Earthquake and Other Earth Movement Are Commonly Excluded
Earthquake damage generally requires separate coverage rather than standard homeowners insurance.
Catastrophic earthquake and earth-movement damage generally fall outside standard homeowners coverage. Protection may be available through a separate earthquake policy, endorsement or state-specific program.
Earth-movement wording can extend beyond shaking from an earthquake. Depending on the policy and state, exclusions can address landslide, sinking, rising, shifting or other movement of the ground.
Do not assume every type of ground loss is handled identically nationwide. Sinkhole and mine-subsidence rules, for example, can be state-specific and may involve separate statutory or insurance programs.
For earthquake risk, compare:
- Dwelling coverage
- Personal-property coverage
- Loss-of-use coverage
- Percentage deductibles
- Retrofit discounts where available
- Coverage for masonry, foundations or other restricted property
Premium and deductible tradeoffs also matter when evaluating earthquake insurance costs.
Wear and Tear, Deterioration and Neglect Are Not What Home Insurance Is For
Homeowners insurance is designed primarily for covered losses, not for the predictable cost of owning and maintaining a house.
Wear and tear, maintenance and neglect are common exclusions. Rotted boards, worn roofs and failing window seals are examples of deterioration that a homeowners policy generally is not designed to repair.
Examples can include:
- An old roof reaching the end of its useful life
- Rot developing over time
- Corroded plumbing
- Cracked seals or deteriorated caulking
- Mechanical breakdown caused by age or ordinary use
- Damage that becomes worse because a known problem was not addressed
An excluded worn component can still trigger a separate sudden loss that may be covered.
The same principle applies to water-damage coverage: the failed source and the resulting damage can receive different treatment.
Termites, Rodents and Infestations Are Usually a Maintenance Problem
Termite, insect and rodent damage is another common exclusion.
Damage from rodents, insects and other infestations is generally excluded from standard homeowners coverage rather than treated as a sudden covered loss.
Insurers generally view infestation as something that develops over time and can be prevented or treated through maintenance rather than as a sudden accidental loss.
Examples include:
- Termites damaging structural wood
- Rodents chewing insulation or building materials
- Insect infestations damaging the home
- Long-term nesting or contamination damage
A resulting event can create a more complicated claim. For example, if an excluded animal-related condition leads to a separate covered peril, the policy language governing resulting loss becomes important. Do not assume either automatic coverage or automatic denial without reviewing the contract.
Slow Leaks, Sewer Backup and Mold Can Fall Into Different Gaps
“Water damage” is too broad to tell you whether insurance applies.
Sudden and accidental water damage may be covered while gradual leakage or seepage is commonly excluded. Sewer or drain backup also often requires separate coverage rather than relying on the base homeowners policy.
A water-backup endorsement may provide sewer-backup coverage when the base homeowners policy does not.
Three separate gaps can therefore exist:
Gradual Leakage
A pipe, shower seal, roof or foundation that leaks slowly over time can fall under seepage, deterioration, maintenance or neglect language even though a sudden burst pipe would be covered.
Sewer, Drain or Sump Backup
Endorsements can add protection for specified backup events. Check the endorsement limit and deductible because they may be much smaller or different from the main dwelling coverage.
Mold
Mold is commonly excluded or limited, although some policies may provide restricted coverage when mold results from a covered sudden water event. Testing and remediation can also have separate limits.
Coverage therefore depends on the cause of the moisture and the policy’s mold or fungi provisions—not simply on whether mold is present.
Business Use Can Outgrow a Homeowners Policy
Homeowners insurance is a personal insurance contract. Running a business from the property can create property and liability exposures that the standard policy was not designed to insure fully.
Business inventory, supplies and liability can receive limited or no protection under a homeowners policy. Disclose home-business activity to the insurer and review whether separate business coverage is needed.
Potential gaps can involve:
- Business inventory
- Computers and specialized equipment
- Property belonging to customers
- Customers or employees visiting the home
- Professional liability
- Business interruption
- A detached structure used primarily for business
A small incidental business may be addressable through an endorsement, while a larger operation can require a businessowners policy or other commercial coverage.
Tell the insurer how the property is actually used rather than assuming remote work, online sales, inventory storage and customer visits are treated the same way.
Property That May Need Separate or Additional Coverage
Valuables May Be Limited Rather Than Completely Excluded
An expensive item can be “covered” and still leave a large uninsured balance.
Standard homeowners policies can impose special limits on categories such as jewelry, artwork, antiques and other high-value property.
Suppose the policy has substantial overall personal-property coverage but a much smaller theft limit for jewelry. Raising Coverage C alone may not raise that jewelry sublimit.
Possible solutions include:
- Scheduled personal-property coverage
- A higher category limit
- A separate valuables policy
- Updated appraisals when required
A low sublimit is a limit problem, not necessarily an exclusion problem. The appropriate fix may be to raise that sublimit rather than buy a completely different homeowners form.
Review the applicable homeowners endorsements before assuming the policy’s overall contents limit protects every valuable item equally.
Cars and Some Other Property Need Their Own Insurance
Homeowners insurance does not replace auto insurance.
Automobiles and animals are examples of property that generally falls outside the homeowners personal-property coverage section.
Motor vehicles can have policy-defined exceptions for certain equipment or vehicles used to service the residence, so read the definitions rather than treating every machine with wheels identically.
Other property can also have special treatment, including:
- Watercraft
- Trailers
- Aircraft
- Property rented to others
- Property of tenants
The right policy depends on what the property is and how it is used. A tenant’s belongings, for example, belong under the tenant’s renters policy rather than the landlord’s homeowners contents coverage.
Wind and Hail Are Usually Covered—But Not Everywhere
Wind and hail are common homeowners perils, so it would be wrong to list them as standard nationwide exclusions.
But availability can change in high-risk markets.
Coastal homes may need separate windstorm coverage in some markets. Other catastrophe-prone areas can use different underwriting arrangements, deductibles or exclusions.
Hurricane planning makes the distinction especially important because a hurricane can create:
- Wind damage
- Wind-driven rain through a covered opening
- Storm surge
- Surface flooding
The first two may fall under homeowners or separate wind coverage depending on the policy, while storm surge and surface flood belong under flood insurance.
Do not rely on the word “hurricane” to decide which policy pays. Separate the damage by cause.
Some Losses Are Excluded by the Nature of the Act
Standard policies also contain exclusions that receive less attention because most homeowners do not shop specifically around them.
War, nuclear hazard, neglect, intentional loss and certain government action are examples of causes or circumstances that standard policy language can exclude.
You do not need to memorize every low-frequency exclusion; you do need to understand that an open-peril policy does not provide unlimited coverage.
Also watch for coverage that is not completely absent but can be limited. Building-code or ordinance costs, for example, may require or benefit from additional ordinance-or-law protection to pay the increased cost of rebuilding to current codes after a covered loss.
How to Find the Gaps in Your Own Policy
The exclusions page is only the beginning of a useful policy audit.
- Identify the policy form. Determine whether the dwelling and belongings are named-peril or open-peril.
- Read the exclusions section. Note flood, earth movement, water, wear, business and other restrictions.
- Check special limits. Review valuables, business property and other property categories.
- Review every endorsement. Endorsements can restore coverage, add a new exclusion or change a limit.
- Look at deductibles. Covered loss can still leave a large out-of-pocket amount.
- Check catastrophe gaps. Confirm flood, earthquake and wind arrangements rather than assuming the base policy handles all three.
- Review how the property is used. Business, rental, vacancy and renovations can change the risk.
- Ask what changed at renewal. Compare forms and endorsements with the prior year, not only the premium.
Different homeowners policy types can start with different coverage structures before endorsements are applied, so the form itself matters as well as the exclusions.
Frequently Asked Questions (FAQs)
What are the most common homeowners insurance exclusions?
Common exclusions include flood, earthquake or earth movement, wear and tear, neglect, termites and other infestations, and many gradual water losses. Sewer backup and mold can also be excluded or limited depending on the policy.
Does homeowners insurance cover flood damage?
Most homeowners insurance does not cover external flooding such as storm surge, overflowing rivers or surface-water runoff. Flood coverage is available through the NFIP and private flood insurers.
Does homeowners insurance cover earthquakes?
Standard homeowners policies generally exclude earthquake damage. Earthquake protection may be available through an endorsement, separate earthquake policy or state-specific program.
Does homeowners insurance cover wear and tear?
Wear and tear is generally not insured. Insurance generally does not pay to replace property simply because it has worn out, deteriorated or needs routine maintenance. A separate sudden covered loss caused by a worn component can require a different coverage analysis.
Does homeowners insurance cover termites?
Termite and other infestation damage is generally excluded because it develops over time and is treated as a maintenance or prevention issue rather than a sudden insured loss.
Is sewer backup covered by homeowners insurance?
Often not under the standard base policy. Many insurers offer a water- or sewer-backup endorsement. Check its limit, deductible and whether sump-pump events are included.
Are expensive jewelry and artwork excluded?
Not necessarily. They may be covered but subject to special category limits, especially for theft. Scheduling valuable property can provide higher or broader protection.
Does an HO-5 policy cover everything?
Even HO-5 retains exclusions. It generally provides broader open-peril property coverage than HO-3, but exclusions, limits, deductibles and conditions still apply. Major gaps can still include earthquake and flood.
Sources
- National Association of Insurance Commissioners: Consumer Homeowners Insurance
- National Association of Insurance Commissioners: Understanding Your Homeowners or Renter’s Policy
- Texas Department of Insurance: Five Things Your Home Policy Won’t Cover, updated April 2025
- Texas Department of Insurance: Home Insurance Policies — All Risk or Named Peril, 2025
- Texas Department of Insurance: Homeowners Insurance FAQ, 2025
- California Department of Insurance: Residential Insurance — Homeowners and Renters
- Washington Office of the Insurance Commissioner: Flood Insurance and Sewer Backup
- National Flood Insurance Program: What Is a Flood?