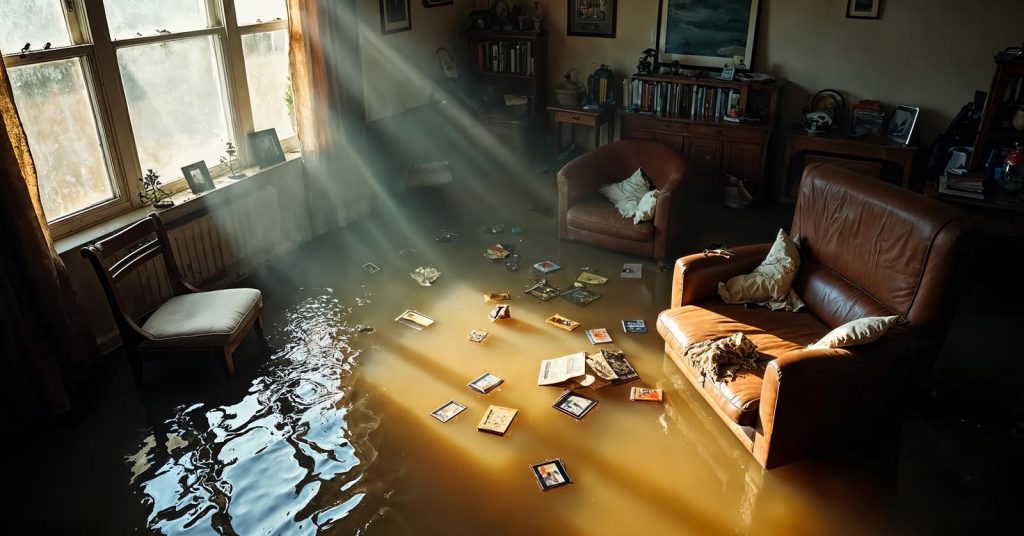
The first few hours after home damage can shape the rest of the claim. Evidence disappears during cleanup, emergency repairs cover damaged areas, contractors begin making decisions and displaced families start spending money before they know what the policy will reimburse.
Strong claim files preserve that information from the start. Your job is not to prove the insurer owes every dollar you request, but to create a clear record of what happened, what was damaged, what you spent and why the policy should respond.
1. Make the Property Safe and Document the Damage
Safety comes before insurance paperwork. Do not enter a building that may be structurally unsafe, electrically hazardous, contaminated or otherwise dangerous simply to take photographs.
Once it is safe, document the loss before conditions change.
Take wide and close-up photos or video of:
- Each damaged room
- The exterior of the home
- Roof, siding, windows and doors when safely visible
- Water lines or staining
- Damaged furniture and belongings
- Appliances and electronics
- Debris and damaged building materials
- Temporary repairs before and after the work
Make a list of damaged property and photograph or record the damage. Keep damaged property until the insurer gives permission when it is safe and practical to preserve it.
2. Report the Claim Promptly
Contact the insurance company or agent as soon as reasonably possible after discovering a potentially covered loss.
Reporting deadlines vary by state, and policies can impose their own notice and proof-of-loss requirements. Claim deadlines are not governed by a single nationwide rule such as “you always have one year,” so check the policy and applicable state requirements promptly.
When you report the claim, have available:
- Your name and contact information
- Policy number if accessible
- Property address
- Date and approximate time of loss
- What happened
- Initial description of damage
- Whether the home is safe to occupy
- Emergency repairs already made
Request:
- The claim number
- The name and contact information of the assigned adjuster when available
- What documents the insurer needs
- Whether a formal proof-of-loss form will be required
- Any applicable deadlines
- Instructions before discarding property or starting permanent repairs
- How additional living expenses should be documented if the home is uninhabitable
Maintain a claim log from this point forward. Record dates, names, phone calls, emails, inspections, requested documents and what each person told you, and save copies of claim correspondence in the same file.
3. Prevent Further Damage Without Erasing the Evidence
Homeowners policies commonly require reasonable steps to protect damaged property from further loss.
Reasonable steps can include:
- Covering a damaged roof with a tarp
- Boarding a broken window
- Stopping an active plumbing leak when safe
- Removing standing water
- Securing an opening against weather or theft
- Moving undamaged belongings away from an affected area
Make reasonable temporary repairs needed to prevent additional damage and save the receipts. Avoid unnecessary permanent repairs until the insurer has had a reasonable opportunity to inspect the loss, unless safety or emergency conditions require otherwise.
Photograph the condition before emergency work whenever possible. Then photograph the temporary repair and retain invoices and receipts for materials and labor.
4. Build an Inventory of Damaged Personal Property
Severe contents losses can involve hundreds or thousands of individual items. Reconstructing that list after a fire or major water loss is much harder than maintaining a home inventory before anything happens.
For each damaged or destroyed item, record as much as you reasonably can:
- Item description
- Brand and model
- Approximate age
- Quantity
- Original purchase information if known
- Current replacement price
- Photos or video
- Receipts, statements or other ownership records
Destroyed records can sometimes be reconstructed from old photos, account records and current retailer pricing.
Do not assume the insurer will value every item at its current new purchase price. Claim value depends on whether the policy settles personal property at replacement cost or actual cash value, as well as special limits, exclusions and deductibles.
High-value property may be subject to special sublimits under the base policy. Jewelry, collectibles, firearms, fine art, cash and business property can be subject to limits below the overall personal-property limit.
5. Prepare for the Insurance Adjuster’s Inspection
Your insurer may assign an employee adjuster or an independent adjuster working for the insurer to inspect the property and evaluate the claim.
Before the inspection:
- Organize photos and videos
- Prepare your damage list
- Gather emergency-repair receipts
- Collect contractor estimates you already have
- Identify areas that are difficult to access
- Write down questions about coverage and deductibles
Be present for the inspection when practical and walk the property with the adjuster so important damage is not missed.
Have the contractor’s scope available during the adjuster’s review when a contractor has already inspected the property. When there is disagreement about the damage or required repair work, having the contractor and adjuster compare scopes can help isolate the disputed items.
An adjuster’s inspection is not the same thing as a contractor’s final repair proposal. California DOI distinguishes the scope of loss—the damaged areas, measurements, materials and workmanship—from the finished priced estimate.
6. Track Additional Living Expenses Separately
Loss of Use (Coverage D) may reimburse qualifying additional living expenses when a covered loss makes the home uninhabitable, subject to the policy.
Coverage D generally reimburses reasonable additional expenses caused by displacement—not every household expense you continue to pay.
Examples may include:
- Hotel or temporary rental costs
- Additional meal expenses
- Laundry
- Storage
- Extra transportation caused by the temporary location
- Other covered increases necessary to maintain the household during displacement
Save receipts and use a simple spreadsheet showing normal spending compared with increased spending. Track housing, food, laundry and other displacement-related costs separately from normal household expenses.
Immediate cash needs after displacement are a reason to ask whether the insurer offers an advance.
Coverage depends on the cause of loss. NFIP standard flood policies, for example, do not provide additional living expense coverage, so do not assume homeowners Coverage D applies when the home is uninhabitable because of an excluded flood loss.
7. Review the Estimate and Claim Payment Line by Line
Do not evaluate a settlement only by looking at the total check.
Compare the insurer’s estimate with the visible damage, your inventory and contractor pricing. Look for:
- Missing rooms or damaged areas
- Incorrect measurements
- Material-quality differences
- Labor quantities
- Personal-property items that were omitted
- Applied deductible
- Depreciation
- Special limits
- Coverage limits
- Excluded portions of the loss
Have the adjuster explain the settlement offer and how repair and replacement estimates were calculated, especially when the numbers differ from contractor estimates.
The First Check May Not Be the Final Payment
An initial insurer check may be an advance rather than the final settlement, particularly on a large property claim.
Replacement-cost claims can also be paid in stages. Your insurer may initially pay the actual cash value of damaged property and release qualifying recoverable depreciation after you complete repairs or replace belongings according to the policy.
An initial check smaller than the contractor’s replacement estimate is not automatically evidence that the claim was underpaid. First determine:
- Whether depreciation was withheld
- Whether that depreciation is recoverable
- What deductible was applied
- Whether the payment is labeled partial, advance or final
- What documentation is needed for the next payment
Your Mortgage Company May Be Named on a Structural Claim Check
When a mortgage lender has an interest in the damaged home, a structural claim payment may include the lender as a payee. Claim proceeds can then be held in escrow and released in stages as rebuilding progresses, depending on the servicer’s process.
Mortgage involvement can slow access to claim funds, so contact the servicer early for its insurance-loss process, inspection requirements and draw schedule. Servicer release procedures are separate from the insurer’s calculation of the covered claim.
8. What to Do if the Settlement Looks Too Low
Different estimates from a contractor and insurer do not necessarily mean either side is wrong. They may be using different measurements, materials, labor assumptions or scopes of work.
Make the disagreement specific.
Ask the adjuster:
- Which damaged item or repair was not covered?
- Which policy provision supports that decision?
- What measurement or unit price was used?
- How was depreciation calculated?
- Can the estimate be supplemented if additional covered damage is discovered?
- What documentation would support reconsideration?
Provide competing contractor estimates, photos, invoices or expert reports when they directly support the disputed work.
If the dispute is about the amount of loss, check whether the policy contains an appraisal clause. Appraisal can be one mechanism for resolving a disagreement over claim value, although its scope and effect depend on the contract and applicable state law.
A public adjuster is another option in some states. Public adjusters work for the policyholder for a fee, are not government employees or attorneys, and are regulated differently by state. Verify licensing with your state insurance department before hiring one.
9. How to Respond to a Claim Denial
A denial should be evaluated against the policy language, not simply accepted or rejected based on whether the loss seems unfair.
Ask for the insurer’s written decision and identify:
- The cause of loss the insurer determined
- The exclusion or coverage provision it relied on
- Any condition it says was not satisfied
- Whether only part of the claim was denied
- What evidence could change the decision
Then compare that explanation with the policy that was in force on the loss date, including endorsements.
If you believe the insurer has delayed, denied or underpaid the claim improperly, first use the insurer’s internal escalation process. If that does not resolve the issue, your state insurance regulator is the appropriate consumer-regulatory channel.
State insurance departments can investigate complaints involving issues such as unfair claim delays or denials, failure to honor the policy and lack of timely communication. Procedures vary by state.
Regulators do not act as your private attorney and cannot resolve every contract dispute. Major losses, litigation issues or approaching legal deadlines may require advice from a qualified attorney in your state.
Homeowners Insurance Claim Checklist
| Stage | Action |
|---|---|
| Immediately | Make the property safe and stop active sources of additional damage when possible |
| Before cleanup | Photograph and video the damage |
| Report | Contact the insurer promptly and obtain a claim number |
| Mitigate | Make reasonable temporary repairs and save receipts |
| Inventory | List damaged belongings and collect ownership/replacement information |
| Adjuster | Walk the property, identify all damaged areas and keep a copy of the insurer’s estimate |
| Displacement | Track additional living expenses separately |
| Settlement | Check scope, pricing, depreciation, deductible, limits and exclusions |
| Repairs | Keep invoices and proof of completed work for replacement-cost payments or supplements |
| Dispute | Ask for the exact policy and calculation basis in writing, then escalate if necessary |
Also confirm which homeowners insurance deductible applies before assuming how much of the loss the insurer will pay. A wind, hail or hurricane claim can trigger a different deductible from a fire or theft claim.
Frequently Asked Questions (FAQs)
How soon should I file a homeowners insurance claim?
Report a potentially covered loss promptly. Policies and state law can impose notice or proof-of-loss deadlines, so the applicable deadline must be checked for the specific claim and jurisdiction.
Should I take photos before filing the claim?
Yes, when it is safe. Photograph and video the damage before cleanup and temporary repairs whenever possible. Preserve damaged property for inspection unless safety or health concerns make that unreasonable.
Can I repair my home before the adjuster comes?
Make reasonable temporary repairs needed to prevent additional damage, such as tarping a roof or boarding a window. Avoid unnecessary permanent repairs before the insurer has had an opportunity to inspect, and save all receipts.
Do I have to pay my homeowners deductible to the insurance company?
Your deductible is generally subtracted from the covered claim calculation rather than paid to the insurer as a separate bill. You remain responsible for that portion of the loss when paying for repairs or replacing property.
Why is my insurance check lower than the repair estimate?
Possible reasons include the deductible, depreciation, an initial ACV payment, missing or disputed scope items, policy limits or excluded work. Ask the adjuster for a line-by-line explanation before assuming the payment is final.
What is a proof of loss?
A proof of loss is a formal statement to the insurer about the loss and the amount claimed. Whether and when one is required depends on the policy, state rules and the insurer’s request.
Can I challenge a homeowners insurance settlement?
Potentially. Identify the specific disputed scope, price, depreciation or coverage decision and provide supporting documentation. Appraisal, a public adjuster, a regulatory complaint or legal advice may also be available, depending on the policy and state.
What if my insurer denies the claim?
Request the written reason and the exact policy provision supporting the denial. If internal review does not resolve the problem, your state Department of Insurance can accept consumer complaints and investigate issues within its authority.
Sources
- National Association of Insurance Commissioners: What You Need to Know When Filing a Homeowners Claim
- National Association of Insurance Commissioners: A Consumer’s Guide to Home Insurance
- National Association of Insurance Commissioners: How Do I File a Complaint Against My Insurance Company?, March 2026
- Texas Department of Insurance: Home Insurance Guide, updated 2026
- Texas Department of Insurance: Tips for Filing a Claim
- Texas Department of Insurance: Hail Damage to Your Home or Car? What to Do Next, updated December 2025
- California Department of Insurance: Residential Property Claims Guide, revised February 2025
- Washington Office of the Insurance Commissioner: Steps to Take After Home Damage or a Loss